
Marriott's Earnings Beat Shows Why It's More Than a Bet on Travel Demand
- Marriott beat third-quarter earnings expectations and raised its full-year 2026 outlook.
- Hotel conversions and growing franchise and credit card fees are helping Marriott expand without the cost of building every new property.
- Marriott's valuation remains a concern despite strong earnings growth and an improving outlook.
Marriott International Inc. (NASDAQ: MAR) earnings for the third quarter of 2026 topped expectations across the board. The hotel giant reported adjusted earnings per share (EPS) of $3.02, up 22% from $2.47 a year ago. That beat the consensus estimate of $2.84. Revenue rose 8% to $7.01 billion.
Worldwide revenue per available room (RevPAR) grew 6.5%. The U.S. & Canada led with 7.4% growth, while international markets rose 4.4%. The Luxury category stood out. Systemwide luxury RevPAR in the U.S. & Canada jumped 11.9%, and The Ritz-Carlton posted a 14.6% gain.
Not every region contributed. Middle East & Africa RevPAR fell 5.3% amid the ongoing conflict, and Greater China was roughly flat. Still, management said Middle East trends improved meaningfully from the second quarter. The company also credited the World Cup with a boost in June and July.
Management raised its full-year outlook anyway. Marriott now expects 2026 RevPAR growth of 4.5% to 5%. Adjusted EPS guidance moved to $12.07–$12.14, up from $11.64–$11.81. But the headline numbers don't tell the whole story. Investors often treat Marriott as a bet on travel demand. The third quarter showed that Marriott's fee revenue is growing faster than RevPAR.
How Hotel Conversions Are Fueling Marriott's Growth
Capital expenditures are a major consideration for companies investing heavily in infrastructure. Those costs can reduce free cash flow or require additional financing, particularly when interest rates are high.
That's one reason Marriott's business model warrants a closer look. Hotel owners generally cover construction costs, allowing Marriott to expand without making those investments itself. Marriott's third-quarter report highlighted another advantage: converting existing properties to its brands helps the company expand more quickly without waiting for new hotels to be built.
Marriott brought many existing independent properties into its system. These conversions can add rooms and begin generating fees sooner than newly constructed hotels.
Conversions made up over a third of signings and over 40% of openings in the first nine months of 2026. Marriott also reported a record year-to-date global organic signings. Net rooms grew 4.6% year over year to nearly 1.834 million. The development pipeline hit a record of more than 634,000 rooms.
That doesn't mean growth is free. Marriott still expects $1.25 billion to $1.35 billion in investment spending this year. That includes contract acquisition costs paid to win new deals. Those expenses still affect Marriott's cash flow, even though hotel owners generally cover construction costs.
Marriott's Fee Revenue Is Growing Faster Than RevPAR
The capital-light model shows up in the fees that Marriott collected.
Gross fee revenues rose 14% to $1.52 billion, more than double the pace of RevPAR growth.
Franchise fees climbed 15% to just over $1 billion.
Incentive management fees jumped 22% to $181 million, with every region posting gains.
A big driver was co-branded credit card fees. These fees aren't directly tied to hotel occupancy. They're also driven by how many people carry a Marriott card and how much they spend. Marriott Bonvoy reached about 309 million members. That audience helps make Marriott's co-branded cards attractive to issuers.
That fee growth also supported earnings. Adjusted EBITDA rose 12% to $1.51 billion. Marriott repurchased 3.5 million shares for $1.3 billion in the quarter, and its diluted share count fell about 4% year over year. The company expects to return at least $4.8 billion to shareholders in 2026. One caveat: debt rose to $16.8 billion from $16.2 billion at year-end, and net interest expense climbed 13%.
Marriott's Valuation Remains a Concern for Investors
The largest concern for Marriott shareholders coming out of earnings is valuation. MAR is now trading about 3.5% below its 52-week high with a price-to-earnings ratio around 43.
Since the report, several analysts have raised their price targets for Marriott, although their outlooks on the stock remain mixed.
That mixed outlook highlights a broader question about how investors should value Marriott. If investors view Marriott as a capital-light licensing and loyalty business, the valuation may make sense.
However, as a cyclical hotel stock, it's priced for perfection. But travel demand has held up in 2026, supporting Marriott's growth outlook even if its valuation remains a concern.
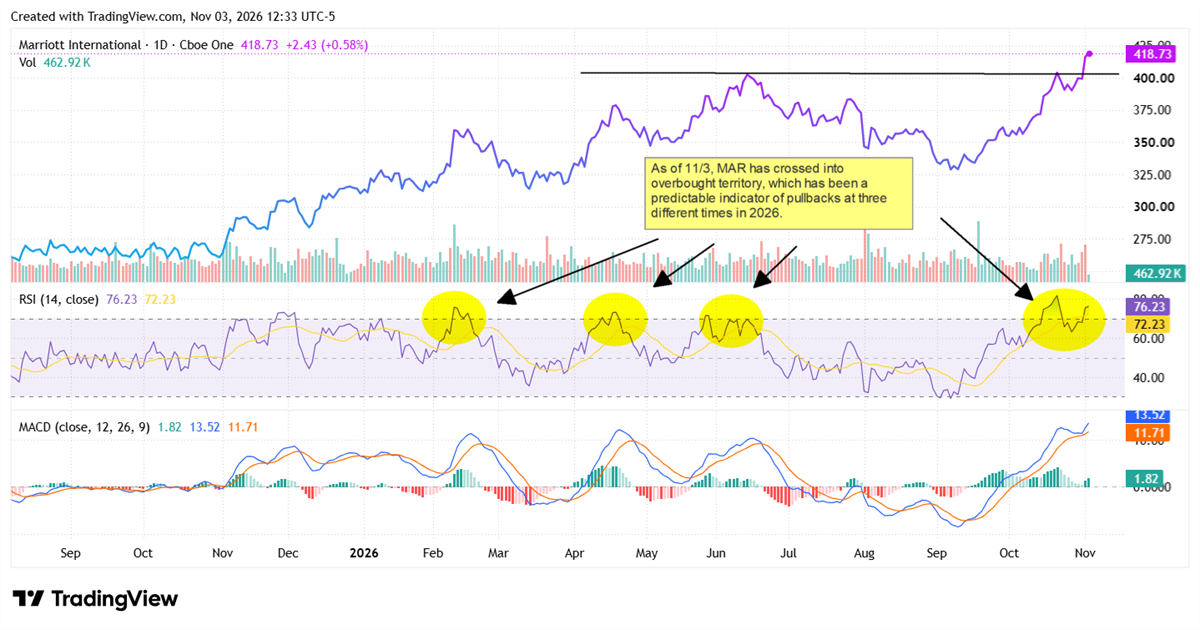
The MAR chart shows momentum is on the side of the bulls. The moving average convergence divergence remains above its signal line, so momentum hasn't rolled over yet.
However, the relative strength index (RSI) sits near 76, firmly in overbought territory. The last three times RSI pushed above 70, in February, April, and June, shares pulled back.
That means another pullback wouldn't be surprising. In that event, the $400 level that capped the stock in June could act as support.
Stocks Mentioned in this Article
| Company | Current Price | Price Change | Dividend Yield | P/E Ratio | Consensus Rating | Consensus Price Target |
|---|---|---|---|---|---|---|
| Marriott International (MAR) | $424.87 | +2.0% | 0.69% | 42.40 | Moderate Buy | $394.48 |